


Seasonal Stock Selling Is Not Working
- Aug 29
- 6 min read

Stocks and bonds advanced this week, though they both pulled back on Friday. Last week, I discussed the big rally in Bitcoin (and IBIT).
A Look at the Market
The S&P 500 has returned 13.4% with dividends included, and the price is up 12.8% for SPDR S&P 500 ETF (SPY) in 2026 so far. This leaves the market on track to post a return for the full year right at 20%. At the same time, iShares Core US Aggregate Bond ETF (AGG) has declined in price in 2026. With dividends included, the return has been -0.1%, which is well below cash.
While Bitcoin did advance slightly during the week, precious metals did decline. Silver remains down year-to-date, while Gold is marginally higher now. Gold miners are up slightly more than the S&P 500 though they are not up as much as the Russell 2000. The S&P 500 made a new all-time high in mid-August. While it did advance this week, it did not make a new high. Looking at the 11 GICS sectors, here is the month for the 2026 high for each one:

5 of the 11 sectors have posted 52-week highs during August, as the S&P 500 has done. Those 5 sectors include the very strongest one this year, Energy (+42.1%), and they currently represent 35.2% of the S&P 500 by market cap. The largest sector remains Technology at 38.0%, which is bigger than these five sectors that recently made 2026 highs.
Looking at the top 10 names in the S&P 500 now (ranked by size), here is when they set a 2026 high:

The largest names in the index currently have averaged a return of 27.7% during 2026 including dividends, but this has been boosted by Micron Technology (MU), which was not in the top 10 at the beginning of the year. Two are down!
Two did set new 2026 highs in August, but neither is ahead of the S&P 500 by much. In fact, one is up less than the S&P 500. The big winner, a semiconductor stock, set its high in June and is currently 23.1% below it.
Looking at the S&P 500 a bit differently, it is just 1.1% below the all-time high, and the S&P 100 is only 0.8% below. The larger-cap index, though, is below the S&P 500 return year-to-date, returning just 11.6%. Over the past few years, the S&P 500 has lagged the S&P 100 substantially. The big story this year remains the falling apart of the leadership by the very largest stocks. I wrote about this in June, discussing how the Magnificent 7 is dying. Since then, Microsoft (MSFT), which was down year-to-date at that time, has soared by 31.7%, while Tesla (TSLA) has dropped 14.2%. MU has dropped 5%, and Broadcom (AVGO) and Alphabet are down too. SPY since then has returned 4.0%, with Microsoft and three other stocks returning more.
One of the big stories this week was that the largest stock, NVIDIA (NVDA) reported. It was a strong quarter compared to what was expected, and the guidance was boosted. The stock rallied by 1.3% for the full week, but it ran up a lot on Thursday after the report on Wednesday night. Note that it did not make a new high and is up only slightly more than the S&P 500 year-to-date. Since the end of 2022, it has soared 1390%, outpacing the 110% gain in the S&P 500.
In two of the past three full years, the S&P 500 has returned at least 20%, and it is on track to perhaps do that a fourth year in 2026. In 2023, the total return was 26.2% and it was 24.9% in 2024. Last year, it gained less, returning 17.7%. NVDA softened last year two, gaining just 38.9% but rising to about 8% of the S&P 500. The "sell in May and go away" trading strategy has not exactly worked this year, with the S&P 500 returning 7.3% since the end of April. NVDA has returned 9.1%, and semiconductor stocks, as measured by iShares Semiconductor ETF (SOXX) have returned 10.3%. Perhaps ironically, iShares Expanded Tech-Software Sector ETF (IGV) has returned a stellar 30.5% since the end of April, posting a 2026 high after being decimated earlier in the year.
Of course, the seasonal trading strategy is still in process, with the end still two months away. This week, the largest company in the S&P 500 reported very strongly, and the market didn't exactly explode higher. The Q3 earnings reports for the quarter ending September 30th, which is a month away, will be reported starting in late October (for those who follow the six-month rule).
I am not a believer in seasonal strategies working all the time, and I do appreciate that things can and do change. The big story about stocks in 2026 is how the very largest stocks aren't doing as well as the rest after years of domination. The market seems toppy, but nobody, including me, knows if it has topped. AI has been a big driver of stocks this year and over the past few years, though it is not the only driver. AI boosts demand for semiconductors, and the S&P 500 is very exposed to that sub-sector. Many are saying that NVDA is cheap, and they also view other semiconductor companies this way. I see NVDA as very large in absolute terms ($5.3 trillion market cap) with a lot of embedded long-term capital gains for many investors. NVIDIA and semiconductor companies are a big part of many ETFs now, and this exposes investors to potential negative things like pushback on data center construction and more.
ETF Model Portfolio Update
This ETF model portfolio, which is measured against 60% SPY and 40% AGG, is up relative to its benchmark. This week, I did one trade again, which was published on here instead of on my Seeking Alpha blog. For those who would like real-time alerts (free of charge for now), just subscribe to the blog.
I posted no articles on ETFs or stocks this week, though I wrote a lot about some things at TalkMarkets:
Going into the week, my model portfolio equity exposure totaled 29.2%, spread out across two ETFs. Here is what I did this week:
Monday: I exited Vanguard Short-Term Treasury Index ETF (VGSH) and added to Vanguard Short-Term Inflation-Protected Securities Index ETF (VTIP) and to iShares TIPS Bond ETF (TIP).
Tuesday: I reduced PIMCO 15+ Year US TIPS ETF (LTPZ) and then ProShares S&P 400 Mid-Cap 400 Dividend Aristocrats ETF (REGL) and added to ProShares Russell 2000 Dividend Growers ETF (SMDV).
Wednesday: I sold more REGL and added to LTPZ.
Here is the current model portfolio, which now has 30.9% equity exposure in two ETFs and fixed income exposure in three TIPS ETFs that total 68.3%:
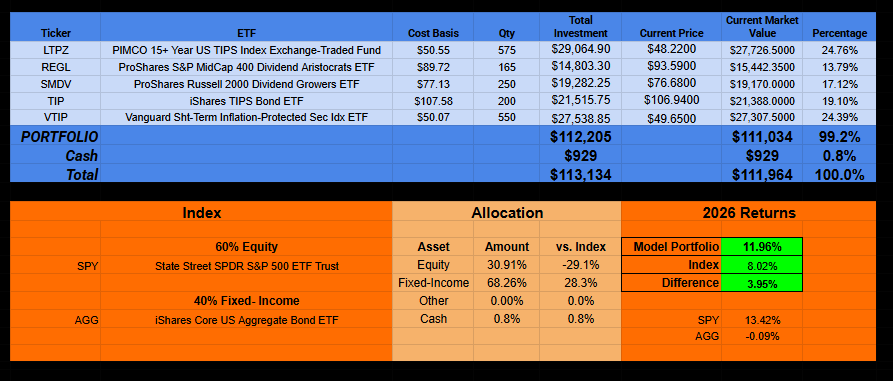
I have been wrong this year, at least so far, as stocks keep rallying. The rally had been until Friday nine weeks ago (June 5th), when stocks had their worst day of the year. Since then, the S&P 500 has made a new high. Small-caps did again make a new high two weeks ago too. Despite being underweight stocks all year, my return relative to the 60/40 index is higher by about 4.0% in almost eight months. As the S&P 500 rose this week and the Aggregate Bond Index rose slightly, the model portfolio, which was about unchanged, underperformed the index.
The year-to-date strong relative performance is not due to superior returns on my current equity ETFs. My TIPS ETFs have done okay relative to AGG, but they aren't exactly boosting the return. VGSH isn't helping too much either. So, what has it been? I have had positive returns from three ETFs, two of which I no longer hold and one of which is down a lot year-to-date that I just repurchased recently, and there has been some good trading.
How I Can Help You
I enjoy analyzing ETFs and stocks, and I like sharing my thinking in writing. I was considering starting a subscription service or joining one that is already being published. What things would you as an investor like to see offered?
If you are an investment professional, I would like to work with you as well. I can help educate financial consultants about the ETFs, and I can work with management at investment firms to help create model portfolios or potential ETF investments. Please let me know if your firm would be interested in this.
My ETF articles at Seeking Alpha, written under the alias The Intelligent ETF Investor, shared a lot of my ideas. I continue to share those ideas here on this blog.


Comments